Private Health Plans
Health protection without waiting for open enrollment
Licensed advisor, in your language
Private health plans for Latino families: from major medical to limited-benefit everyday plans, based on your budget. Availability varies by state: in a free appointment, one of our benefits consultants on Carlos J. Torres's team reviews your case and tells you which plan fits you.
2013
protecting families since
60+
life and health carriers
BBB A+
BBB accredited
What is a private health plan?
It is a health plan you get from a private insurer through an agency like ours, instead of through HealthCare.gov or your state's marketplace. Benefits, provider network and price depend on the plan and on the state where you live.
Many families look for one when their marketplace plan goes up in price, when they no longer get financial help to pay for it, or when they want to compare before renewing. Every case is different, so we don't publish plan details or prices here: what fits you depends on your state, your age and who is included.
At Latin Prime Financial Group we work with more than 60 life and health carriers. At your appointment, a benefits consultant on Carlos J. Torres's team reviews your situation, explains what the plan that fits you covers, what it excludes and what you would pay, and tells you honestly if an ACA marketplace plan suits you better.
Private plan vs. ACA marketplace plan
It's not better versus worse: they are two different paths. At your appointment we see which one suits you.
If you qualify for an ACA plan with good financial help, it is usually the more convenient option, and we tell you so. Marketplace rules change every year: check them on HealthCare.gov.
How to start
A short process, with no obligation.
Book your appointment
Pick the day and time that work for you. It's free.
We review your case
A benefits consultant on Carlos J. Torres's team reviews your situation: your current plan, your budget, your doctors and your medications.
We compare honestly
If an ACA plan suits you better, we tell you. The goal is for you to choose well.
You decide
No rush. If no option suits you, we tell you that too.
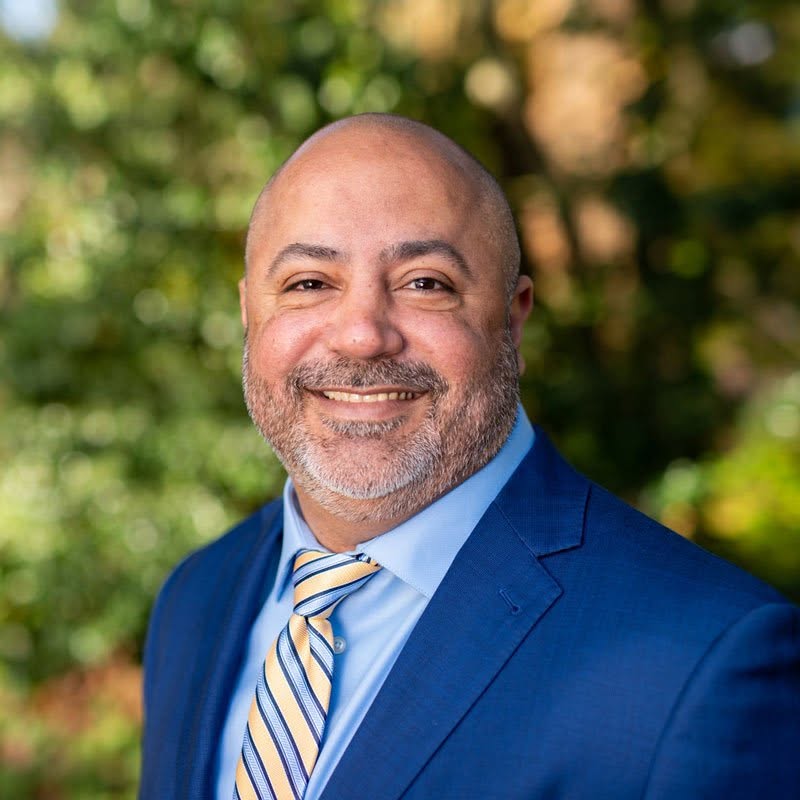
Carlos J. Torres
Licensed agent · Founder
The person you meet in the consultation. In your language, no middlemen, no sales script.
NPN 16975302
Types of private plans we offer
The right one depends on your profile: your health, your budget and your state. Here are the types, in plain words:
Major medical: broad coverage for doctor visits, hospital and prescriptions, with a deductible and a yearly out-of-pocket maximum. Offered based on your profile.
Doctor-visit plan: primary care, specialist, urgent care and lab with a fixed copay. It doesn’t cover the hospital.
Hospital plan with a deductible: fixed copays for visits; hospital and surgery are paid with a deductible and have a set number of days per year.
Hospital plan with a fixed copay and no deductible: you pay a set amount per hospital admission, with a set number of days per year. Some cover maternity after a 12-month waiting period.
Plans for higher budgets: other combinations of deductible, coinsurance and hospital days, which we review with you in the appointment.
Plans 2 through 5 have limited visits, hospital days or services and some exclusions; limited-benefit plans are not traditional major medical insurance. Before you decide, we give you in writing what the plan that fits you covers and doesn’t cover.
What we do at your appointment
- We review the plan you have today, what you pay and what worries you about next year.
- We check which private plans are available in your state for your case.
- We explain what it covers, what it excludes and what you would pay, in plain words and before you sign anything.
- We check whether your doctors and medications are included in the plan.
- If an ACA marketplace plan suits you better, we tell you and help you enroll.
- We help you in Spanish or English, by phone or video, with no pressure to decide.
Questions to ask before choosing any plan
- What does it cover and what does it exclude? Always ask for the plan's summary of benefits.
- What is the deductible and the most I would pay out of pocket in a year?
- Are my doctors, clinics and hospitals in the plan's network?
- How are my medications covered?
- When does coverage start, and what happens with a condition I already have?
- What would I pay when I use the plan: visits, urgent care, lab work or a hospital stay?
Myths that confuse many families
Let's clear up what is most often misunderstood about health insurance.
If I no longer qualify for the ACA subsidy, I have no options.
There are two kinds of private plans: major medical and limited-benefit everyday plans. Availability varies by state; at your appointment we see which one fits you.
All plans cover the same things.
No. Benefits, network and what you pay when you use the plan change from one plan to another. That's why you need to review the summary of benefits.
The cheapest plan is the best one for me.
Not always. A low premium can come with a high deductible. What matters is how much you'd pay in total based on how you use the plan.
Common mistakes when choosing a health plan
- Choosing only by the monthly premium, without looking at the deductible or what you'd pay when you use the plan.
- Not checking whether your doctors and hospital are in the network.
- Not asking how your medications are covered.
- Missing enrollment dates and being stuck for months without being able to change.
- Signing without reading the plan's exclusions.
- Not comparing with an ACA plan when you qualify for good financial help.
Is it worth reviewing your case?
Book your appointment if...
- Your current plan goes up in price for 2027.
- You no longer get help paying for your plan.
- You don't have health insurance today.
- You want to compare before you renew.
Another option may suit you if...
- You qualify for an ACA marketplace plan with good financial help: we'll tell you at your appointment.
- You have Medicare: we point you to Medicare.gov or 1-800-MEDICARE to see your options.
- Your employer offers health insurance: it's worth comparing that first.
- You qualify for Medicaid or CHIP in your state: we guide you on how to apply.
- You’re pregnant: limited-benefit plans generally don’t cover an existing pregnancy; we look at major medical, the Marketplace or Medicaid with you.
- You have a serious condition, such as cancer, dialysis or a scheduled surgery: major medical or a Marketplace plan is a better fit.
- You live in California, Massachusetts, New Jersey, Rhode Island or Washington, D.C.: a limited-benefit plan generally won’t avoid the state penalty; we confirm in writing whether the plan counts.
Free consultation
Talk to an advisor, free and in your language
Leave your info and a licensed advisor will contact you to review your options. No obligation.
- 100% free consultation, no obligation
- We help you in Spanish or English
- We reply within 24 hours
Tell us your case
Fill out the form and we will contact you for your free consultation.
Frequently asked questions
Are private health plans major medical insurance?
It depends on the plan. We offer both kinds: major medical insurance and limited-benefit everyday plans, which cost less but have capped visits and hospital days and some exclusions. They are not the same: at your appointment we tell you which kind each plan is, what it covers and what it does not, in writing, and which one fits your budget.
Are they available in my state?
Availability varies by state. Book your appointment and we'll confirm it for your case.
Do private health plans cover the hospital?
Major medical does. With limited-benefit plans it depends: some don’t cover the hospital and others cover a set number of days per year. We tell you in writing before you decide.
Do they cover pregnancy?
Limited-benefit plans generally don’t cover a pregnancy that already exists; some cover maternity only after a 12-month waiting period. If you’re pregnant, we look at major medical, the Marketplace or Medicaid with you.
Do they cover conditions I already have?
It depends on the plan and on your answers to the health questions. We confirm it in writing in the appointment.
Does a private plan help me avoid the penalty for not having insurance?
Only if it counts as minimum essential coverage. In California, Massachusetts, New Jersey, Rhode Island and Washington, D.C., a limited-benefit plan generally doesn’t avoid the state penalty; before you buy, we confirm in writing whether the plan counts. We have a guide on the penalty in our guides section.
How much does a private health plan cost?
It depends on the plan, your age, your state and who is included. We give you a quote at your appointment, with no obligation.
What is the difference from an ACA marketplace plan?
An ACA marketplace plan is purchased on HealthCare.gov or your state's marketplace and may come with financial help based on your income. A private plan is purchased from a private insurer through an agency. At your appointment we see which one suits you.
What should I bring to the appointment?
If you have a plan, its card or summary of benefits; the list of your doctors and medications; and an idea of how much you can pay per month.
Who will help me?
One of our benefits consultants on Carlos J. Torres's team.
Informational content; not legal or tax advice. Plans, benefits, networks and prices vary by state and insurer and are subject to their underwriting and approval. ACA marketplace rules change every year: check them on HealthCare.gov. Latin Prime Financial Group is an independent insurance agency, not affiliated with the government.
Guides that can help
Information verified with official sources.
Book your appointment
Free and with no obligation: we review your case and tell you which plan fits you.
Prefer to text? Send us your question on WhatsApp (689) 800-8978. If you then want an appointment, we set it up with you on Zoom.